Home/News & Intelligence/St. Regis Sunny Isles $463 Million Financing
St. Regis Sunny Isles Secures $463 Million Financing: What It Means for Buyers
Fortune International Group and Château Group have replaced the Bank OZK construction loan on The St. Regis Residences, Sunny Isles Beach with a $463 million package from Madison Realty Capital, according to reporting published October 26. It is the largest loan reported against the project so far, and most coverage stopped at the headline number. This analysis explains what the financing actually changes, what the figures do and do not show, and what a buyer under contract in the South Tower or considering the North Tower should check now.
Refinancing reported October 26, 2026 · Loan terms not disclosed
Independent buyer research · Not affiliated with Fortune International Group, Château Group, Madison Realty Capital, Berkadia or Marriott International
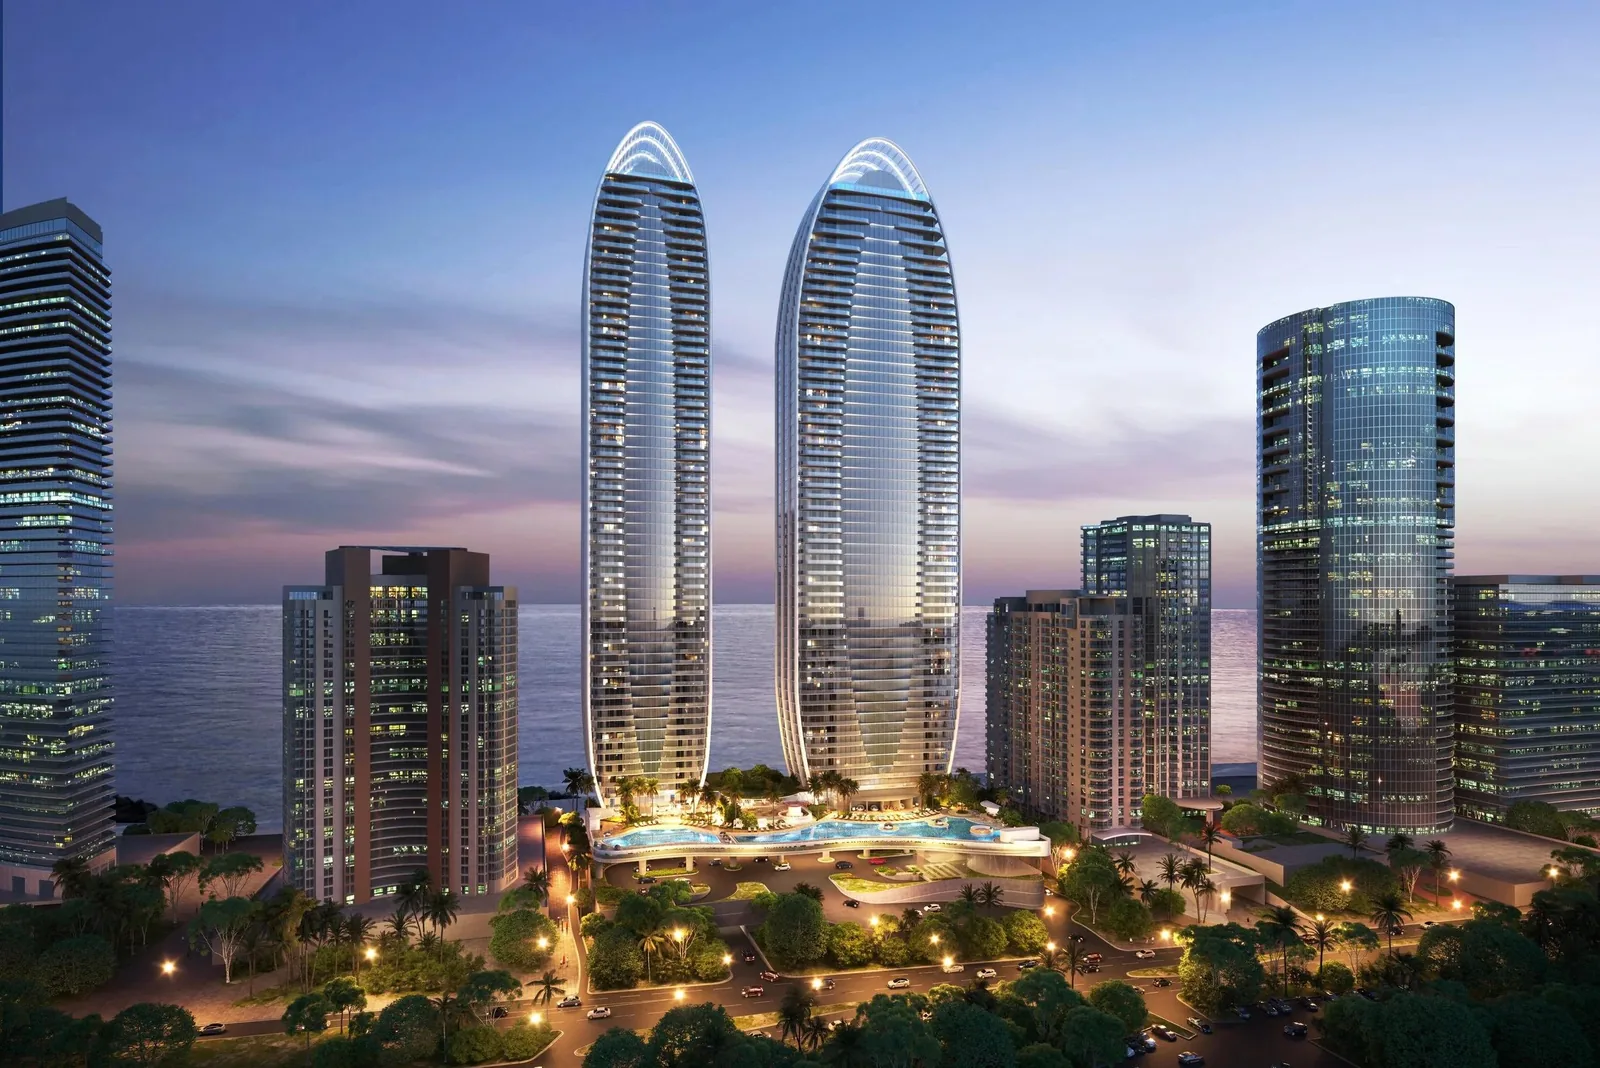
Five answers, as of October 28, 2026
Each answer is expanded, with sources, further down the page.
- What happened?
- On October 26, 2026, Commercial Observer reported that Madison Realty Capital provided a $463 million construction debt package to Fortune International Group and Château Group for The St. Regis Residences, Sunny Isles Beach. Berkadia arranged the financing. The Real Deal carried the same figure the same day, and trade outlets followed on October 27.
- Is it new money?
- Not in the way the headline suggests. The package refinances the existing Bank OZK construction loan, last increased to $418.3 million in December 2025, and funds the remaining construction of the South Tower, including, per The Real Deal, expanded food-and-beverage and hospitality amenities. The $44.7 million difference between the two facility sizes is not confirmed net new borrowing; the financing ledger explains why.
- Where does construction stand?
- The South Tower’s mat foundation was poured July 24–26, 2026, and the developers said the tower would go vertical this year; The Real Deal described vertical construction as under way on October 26. The North Tower had not broken ground as of the same reporting.
- How sold is it?
- About 80 percent of the South Tower’s 170 residences are reported presold, representing more than $1.6 billion in contracts, per Commercial Observer. A Multi-Housing News report is cited for 90 percent (we could not retrieve it), a figure that matches the developers’ December 2025 characterization. Contracts are not closings; the presales section explains the difference.
- What should a buyer do?
- Read the financing as one input, not a verdict. Confirm how your deposits are held under Florida Statutes §718.202, the outside delivery date and your remedies in the purchase agreement, and put independent representation in place before you register for the North Tower.
Why this matters to a buyer. A construction lender’s willingness to replace another lender’s $418.3 million with $463 million means the South Tower passed a second, fresh underwriting in 2026, at a larger size and as what is typically the most expensive phase of construction begins. It does not tell you the loan’s rate, maturity, covenants or guarantees, none of which was disclosed, and it changes nothing in any buyer’s purchase agreement. The sections below separate what the transaction demonstrates from what it is being read to mean.
A $463 million replacement for the Bank OZK loan, not $463 million on top of it
The St. Regis Residences, Sunny Isles Beach has carried Bank OZK debt since 2020. The Arkansas-based bank lent $119 million to the Fortune–Château joint venture that year, added $100 million in April 2024 to bring the commitment to $219 million, and increased it again in December 2025 to $418.3 million, a step Commercial Observer and The Real Deal reported from Miami-Dade property records. At the time of that increase, mortgage documents cited by Commercial Observer showed about $159 million actually outstanding, with the loan upsized by $259.3 million.
That detail is the key to reading the new package. A construction loan is a commitment that the borrower draws against as work is completed and inspected; the stated size is a ceiling, not a balance. In December 2025 the ceiling was $219 million and the balance was roughly $159 million, a gap of about $60 million. The same distinction applies now. The Madison Realty Capital package replaces the Bank OZK facility; it does not sit on top of it. Reporting describes the proceeds as refinancing the existing debt and funding completion of the South Tower, with The Real Deal adding that the developers intend to expand the project’s food-and-beverage and hospitality amenities.
Subtracting one facility size from the other gives $44.7 million. That number is arithmetic on two commitments. It is not confirmed net new borrowing, net loan proceeds or incremental construction funding, because the amount actually owed to Bank OZK at payoff, the closing costs and reserves inside the new loan, and the undrawn portion of the new commitment have not been published. We have not reviewed the recorded mortgage or satisfaction documents for the October transaction, and no outlet we reviewed has reported the loan’s interest rate, maturity, guarantees or covenants.
| Financial item | Reported amount | Basis |
|---|---|---|
| New Madison Realty Capital package | $463 million, described as a construction debt package that refinances existing debt and funds South Tower completion | Reported |
| Previous Bank OZK facility, after the December 2025 increase | $418.3 million maximum commitment | Property records, per press |
| Bank OZK balance when that increase was recorded | About $159 million outstanding; loan upsized by $259.3 million | Mortgage documents, per press |
| Difference between the two stated facilities | $44.7 million | Arithmetic only |
| Confirmed net new borrowing or net proceeds | Not publicly established | Not verified |
| Interest rate, maturity, extension options, guarantees, covenants, developer equity, draw balance | Not disclosed | Undisclosed |
| Separate North Tower land and pre-development loan (City National Bank of Florida, April 2026) | $113.75 million; not part of the $463 million | Developer announcement |
Who is on the other side of the table. Madison Realty Capital is a New York-based real estate lender and investment firm. Its co-founder and managing principal, Josh Zegen, said in a statement carried by Commercial Observer that the transaction reflects the firm’s “conviction in the Sunny Isles Beach submarket.” The firm is also the lender on the $630 million construction loan reported in November 2025 for the Bentley-branded tower at 18401 Collins Avenue, a few blocks south. Berkadia’s Scott Wadler, Michael Basinski, Mitch Sinberg, Matt Robbins, Brad Williamson and Matthew Monahemi arranged the financing; Wadler, Basinski, Sinberg, Robbins and Williamson also arranged the North Tower’s City National Bank loan in April.
Why a lender will commit $463 million to a building that is not finished
Construction debt is not a mortgage on a finished asset. The lender commits a maximum amount; the developer draws it in stages as work is completed, inspected and certified; and the loan is repaid when residences close and the buyers’ purchase funds flow through the closing table. Between the first draw and the last closing, the lender’s collateral is a partly built tower, a stack of purchase contracts and whatever equity and guarantees the sponsors have put behind the project.
That is why presales weigh so heavily in underwriting. A tower that is 80 percent under contract at known prices gives the lender a visible path to repayment: if the building is delivered and the buyers perform, the contracted proceeds, reported at more than $1.6 billion, are the lender’s expected source of repayment. The lender also examines the sponsors’ record, the hard-cost budget and its contingency, the general contractor and what happens if some buyers do not close. None of those inputs is public here, which is why the headline number says less than it seems to.
Two things follow for a buyer. First, financing the project and closing an individual residence are separate events. The loan funds the building; your closing funds your residence; and the construction lender is paid down from closings, normally by releasing its mortgage from each unit as it sells. Second, a lender’s decision is an informed opinion about repayment risk at the project level. It is not a warranty of your delivery date, your finishes or your contract’s terms, and it was not written for you.
South Tower and North Tower are at very different stages
The $463 million and the $113.75 million are separate loans against separate phases. Adding them to $576.75 million and calling the total “project debt” misstates both: one is a construction facility for a tower going vertical, the other a land and pre-development loan for a tower that had not broken ground.
| Item | South Tower | North Tower |
|---|---|---|
| Residences | 170 (175 at the 2023 groundbreaking; reduced under a site-plan revision reported in January 2025) | 150 |
| Stories and height | 62 stories planned; approximately 750 feet, developer figure | 62 stories planned; approximately 750 feet, developer figure |
| Lender | Madison Realty Capital, replacing Bank OZK | City National Bank of Florida |
| Reported facility | $463 million construction debt package, October 2026 | $113.75 million land loan, described by Berkadia as pre-development financing, April 2026 |
| Construction status | Mat foundation poured July 24–26, 2026; going vertical, per the developers and The Real Deal | Not started as of October 26, 2026; groundbreaking “scheduled for early Q4,” per the July 31 developer announcement |
| Sales | About 80 percent presold; more than $1.6 billion contracted (Commercial Observer); 90 percent attributed to Multi-Housing News (not retrieved) | Sales launched February 2024; the collection currently being marketed |
| Completion target | End of 2028, a developer projection relayed by Commercial Observer | Not published by the developers in any source we could verify |
The North Tower’s schedule has moved within 2026: described in February and April as breaking ground “this summer,” then on July 31 as scheduled for early in the fourth quarter, and reported on October 26 as not yet started. That is a modest drift, and it is unremarkable on its own. What a North Tower prospect should notice is that the tower’s construction loan has not been reported; the $113.75 million is a land and pre-development facility. A completion year for the North Tower circulates on third-party listing pages, but we found no developer statement supporting one, so this page does not publish it.
80 percent presold and $1.6 billion in contracts: strong demand, not revenue
Commercial Observer reported on October 26 that about 80 percent of the South Tower’s units are presold, “generating over $1.6 billion”; The Real Deal reported the same percentage. A Multi-Housing News report dated October 28 describes the tower as 90 percent sold. The higher figure matches what the developers said in December 2025, when the Bank OZK increase was reported alongside a “90 percent presold” tower; they went on to describe the South Tower as sold out in February 2026 and “nearly sold-out” in April. We could not retrieve the Multi-Housing News report, and no outlet explains the gap. Different denominators (units versus dollar volume), an underwriting figure versus a marketing figure, or inventory returned to market would each account for it. This page uses the 80 percent figure carried by two outlets on October 26 and treats 90 percent as unresolved.
Either way, a presale is a signed purchase agreement with a deposit. It is not a closing, and $1.6 billion in contracts is not $1.6 billion in the developer’s account. Until a residence closes, the developer holds a contract, and the buyer’s deposits sit with an escrow agent or, where the contract permits, have been applied to construction under the Florida escrow rules described below; the balance of the price arrives only at closing, usually with the buyer’s own financing. Contracted sales support the lender’s underwriting precisely because they are the expected source of repayment, and they will be tested only when the building is delivered and each buyer is asked to close.
Presale commitments do not guarantee that the project will be profitable, that every buyer will perform, that the building will be finished on time or that costs will stay within budget. A buyer who signed in 2022 at a 2022 price and a buyer who signs today have different incentives at closing, and a tower can be both well sold and financially strained if it runs late or over budget. We have not calculated loan-to-value, loan-to-cost or developer margin from these figures, and we would be cautious of anyone who does: the cost side of the project is not public, and reported presales can support a lender’s decision without proving the project is financially safe.
A sanity check, not a financial analysis. Eighty percent of 170 residences is about 136 contracts. Spread across $1.6 billion, that implies an average contract in the region of $11.8 million, which sits well above the project’s published entry pricing of approximately $5 million for remaining residences (the developers do not say which tower) and below penthouse contracts reported far higher. The arithmetic is ours, on reported figures; it says the reporting is internally coherent, nothing more.
What the loan does and does not tell buyers
Reasonable positive readings
- A second institutional lender underwrote the South Tower in 2026 and committed more than Bank OZK had, after the foundation was complete and as vertical construction begins.
- The capital arrives when the expensive phase starts. Structure, enclosure, elevators and interiors are ahead; the least predictable below-grade work is behind the South Tower.
- In the reporting we reviewed, the lender change came with no reported default, lien dispute or litigation on the project, and no outlet characterized it as distress.
- The two towers carry separate lenders, and the same Berkadia team arranged both 2026 loans, which suggests a deliberate capital plan by phase rather than an improvised one.
What remains open
- The loan’s rate, term, maturity, extension options and covenants are undisclosed. A private-lender refinancing can cost more or less than the bank loan it replaces; we do not know which.
- Why the sponsors changed lenders is not stated. A larger facility, more flexible draws or a longer maturity are all ordinary reasons; nothing in the reporting supports reading the change as a problem, and nothing rules out hard negotiation.
- The budget, contingency and developer equity are private. A larger loan can mean a larger scope, higher costs or both; the amenity expansion reported by The Real Deal points to scope.
- The North Tower’s construction loan has not been reported. Its land loan is not a construction loan.
- Nothing in any buyer’s contract changed. The outside delivery date, deposit schedule and remedies are what they were on October 25.
Our reading: the transaction is consistent with a capitalized project moving into vertical construction, which is good news for contract holders and a reasonable comfort for North Tower prospects. It is one input. Treat it the way a lender treats a presale figure: supportive, not dispositive.
Update, October 29, 2026. Two days after this refinancing, on October 28, Fortune International Group and KAR Properties announced an $817 million construction loan from Tyko Capital for Faena Residences Miami on the Miami River, which the sponsors describe as the largest construction loan in Florida history. The two deals together total about $1.28 billion, but only the Faena loan is new construction money; our analysis of the Faena financing separates the new capital from the refinancing and explains what a construction loan does and does not settle for a buyer.
What Florida law does, and does not, do with your deposit
Buyers are often told that “the first 10 percent is protected and the rest can be spent.” The statute is more specific than that in both directions. Florida Statutes §718.202 governs deposits on condominium units sold before the building is substantially complete. What follows is a general explanation of the statute as it reads in 2026, not a review of the St. Regis purchase agreement, which we have not examined for this article.
- 1. The first 10 percent goes to escrow, or to an equivalent assurance
- Payments up to 10 percent of the sale price must be placed in an escrow account, and the buyer is entitled to a receipt on request. For residential condominiums the statute gives the state’s division director discretion to accept other assurances in place of escrow, “including, but not limited to, a surety bond or an irrevocable letter of credit in an amount equal to the escrow requirements of this section.” Under the statute, “escrow” can mean a bond or letter of credit standing behind the deposit rather than cash sitting in an account. The first 10 percent is protected; it is not necessarily untouched.
- 2. Above 10 percent, a special escrow account
- Payments above 10 percent received before completion of construction go into a separate special escrow account controlled by the escrow agent and “may not be used by the developer prior to closing the transaction,” with one exception.
- 3. The construction-use exception
- If the purchase contract so provides, once construction has begun the developer may withdraw the funds above 10 percent to pay “actual costs” of constructing and developing the condominium property, which the statute defines to include demolition, site clearing, permit, impact and utility reservation fees, and the architectural, engineering and surveying fees that directly relate to construction. The funds may not be used for salaries, commissions or salesperson expenses; advertising or marketing; or loan fees and costs, principal and interest on loans, attorney fees, accounting fees or insurance costs. A contract that allows this use must carry a legend in boldface on its first page, immediately above the buyer’s signature: “ANY PAYMENT IN EXCESS OF 10 PERCENT OF THE PURCHASE PRICE MADE TO DEVELOPER PRIOR TO CLOSING PURSUANT TO THIS CONTRACT MAY BE USED FOR CONSTRUCTION PURPOSES BY THE DEVELOPER.” If your contract carries that legend, the developer may withdraw your deposits above 10 percent for those construction costs once construction is under way, so do not assume they remain in escrow. If it does not, they must stay in escrow until closing.
- 4. When the money moves
- Escrowed funds are paid to the buyer, with any interest earned, if the buyer properly terminates under the contract or the statute; to the developer, with interest, if the buyer defaults; and otherwise to the developer at closing, unless the escrow agent has first received written notice from the buyer of a dispute with the developer. If the contract is silent on interest, it goes to the developer at closing.
- 5. Who may hold it
- The escrow agent must be independent of the developer and must be a bank, a savings and loan association, a member of The Florida Bar, a registered real estate broker, a licensed title insurer or title agent, or a lending institution with a net worth above $5 million. Escrow funds may be invested only in United States government securities or in federally insured accounts. “Completion of construction” means a certificate of occupancy for the entire building or the equivalent governmental authorization.
- 6. The remedies
- A contract that does not comply is voidable by the buyer, and if voided, all sums paid must be refunded with interest. A developer who willfully fails to establish, fund or properly withdraw from escrow commits a third-degree felony, and failing to establish or fund the account is prima facie evidence of an intentional violation. The statute was last amended in 2024 by a narrow change to the construction-use subsection that applies only to condominiums whose declarations were first recorded on or after October 1, 2024; which version governs a given project is itself a question for counsel.
Ask your attorney to review
- The deposit schedule and escrow arrangements: how much, when, who holds it, and whether a bond or letter of credit stands in for cash escrow.
- Construction use of deposits above 10 percent: whether the contract permits it and whether the statutory legend appears above your signature.
- Completion deadlines: the outside delivery date, every extension right the developer holds, and how force majeure is defined.
- Remedies for material delay or developer default, and whether return of the deposit is your only recourse.
- Financing contingencies and closing obligations, including what happens if you cannot close when called.
- Project-specific disclosures in the prospectus and condominium documents, including the estimated operating budget and reserves.
- Subordination and lien provisions: how the construction lender’s mortgage, its partial releases and any subordination language interact with your contract and your deed at closing.
Why the statute matters more when financing is in the news
- A refinancing changes the lender whose mortgage sits ahead of your contract. Your protection does not come from the lender’s confidence; it comes from where your deposit is held and what your contract says. The statute sets a floor; the contract sets the terms, and no two Florida pre-construction contracts are identical.
- Where a project’s financing fails, the escrow rules are what stand between a buyer and a creditor queue. Our analysis of the Mandarin Oriental Residences Boca Raton foreclosure shows how that plays out.
- The mechanics of deposits, escrow and completion terms across the market are in our South Florida pre-construction buyer guide.
From groundbreaking to refinancing, and what to watch from here
August 2023 · Reported
South Tower groundbreaking
Then planned at 175 residences; the count moved to 170 under a site-plan revision reported in January 2025. Bank OZK had lent $119 million to the joint venture in 2020.
January 2024 – April 2024 · Reported
Deep foundations; Bank OZK adds $100 million
Pile driving on the oceanfront parcel; the commitment rises to $219 million. North Tower sales launch in February 2024.
December 2025 · Property records, per press
Bank OZK facility increased to $418.3 million
About $159 million outstanding at the time; the South Tower described by the developers as 90 percent presold.
April 23, 2026 · Developer announcement
$113.75 million City National Bank loan for the North Tower
Land and pre-development financing arranged by Berkadia; groundbreaking described as “this summer.”
July 24–26, 2026 · Developer announcement
South Tower mat foundation poured
Announced July 31 with vertical construction to begin this year and the North Tower scheduled to break ground in early Q4. See our analysis of the foundation milestone.
October 26, 2026 · Reported
Madison Realty Capital’s $463 million package refinances Bank OZK
Proceeds fund South Tower completion and, per The Real Deal, expanded hospitality amenities. Terms undisclosed.
Fourth quarter 2026 onward · Projection
North Tower groundbreaking; South Tower rises
Developer schedule, not a commitment.
End of 2028 · Developer projection
South Tower completion target
Closings follow a certificate of occupancy. The date that binds any buyer is the outside delivery date in the purchase agreement, which is often later than the marketing date.
What to monitor. The floor count visible from Collins Avenue, month to month; whether the North Tower breaks ground in the fourth quarter as scheduled, and under what financing; any recorded modification, assignment or satisfaction of mortgage in Miami-Dade County records; and, for contract holders, any deposit installment tied to a structural milestone that vertical construction now brings closer. We will update this analysis if the loan documents become public or when the North Tower’s construction financing is reported.
What a lender’s confidence is worth to you, and what it is not
A $463 million loan is a professional judgment that the project is likely to repay its lender; it says nothing about your residence, your price or your contract. The parties who negotiated it sit on the developer’s side of your transaction, and so does the sales gallery. Someone should read the purchase agreement, the deposit schedule and the escrow terms for you before you sign, and that person should work for you.
TheBuyerRebate.com and Jordan Real Estate represent buyers independently, with attorney-reviewed transaction support. Eligible buyers receive up to 50% of our buyer-agent commission back at closing. A rebate is never guaranteed: it is possible only when buyer-agent compensation is actually received and a rebate is permitted under your buyer-representation agreement, your lender’s approval of credits, and your closing terms — and where no compensation is available there is nothing to rebate. We confirm any figure in writing before you commit. The rebate is a financial benefit at closing; it is not insurance against construction or developer risk, and it does not change anything in the analysis above.
On new development, timing decides it. Developers commonly recognize an outside broker only if the buyer is registered before the first contact with the sales gallery, so contact us before you register for the North Tower; our guide to Miami pre-construction broker registration rules explains why the order matters. How the rebate works, step by step, is in our Florida Buyer Rebate Guide.
Considering the North Tower, or already under contract in the South Tower? Talk to us before your next step.
We will read the purchase agreement, deposit schedule and escrow terms with you, explain what the October financing does and does not change, and confirm your rebate figure in writing before you contact the sales gallery. Eligible buyers receive up to 50% of our buyer-agent commission back at closing.
(786) 550-6294- Considering the North Tower? Contact us before you register with the sales gallery; the order protects both your representation and your rebate.
- Already under contract in the South Tower? We can walk through your deposit schedule, escrow treatment and outside delivery date with your attorney.
- Prefer to message? Email info@thebuyerrebate.com or use the WhatsApp button on this page.
Check Your St. Regis Sunny Isles Rebate
No obligation. This form does not register you with the developer or any sales gallery.
What this page is based on
Research cutoff: October 28, 2026. Loan figures are as reported by the publications named below; where a publication cites Miami-Dade property or mortgage records, that is stated, and TheBuyerRebate.com did not retrieve the recorded instruments. Developer statements are labeled as such. The Florida statute was read in its current (2026) text on the Florida Senate’s statute site and cross-checked against the 2025 text on Justia; the Legislature’s Online Sunshine link below is the canonical reference. Several sources listed in our research brief could not be retrieved from our environment; those relevant to the facts above are identified below.
Source Register
- Commercial Observer · October 26, 2026Madison Realty Lends $463M for First St. Regis Condo in Sunny Isles, Fla.
Supports: $463 million package and Madison Realty Capital as lender; refinancing of Bank OZK debt; 170-unit South Tower that broke ground in 2023; 80 percent presold and more than $1.6 billion; end-of-2028 completion per a sponsor representative; 150-unit North Tower not started, with roughly $114 million from City National Bank of Florida; Berkadia team; Josh Zegen statement. - The Real Deal · October 26, 2026Fortune, Château score $463M loan for St. Regis Sunny Isles
Supports: Bank OZK loans dating to 2020; proceeds to refinance existing loans and expand food-and-beverage and hospitality amenities; vertical construction under way; 80 percent presold; remaining residences from $5.1 million; 4.7 acres and 435 feet of beachfront; Madison as the Bentley Residences lender. Note: the report transposes the two towers’ residence counts relative to the developers’ figures. - Commercial Observer · December 1, 2025Fortune International, Château Group Up Construction Debt for St. Regis Condo Project
Supports: $418.3 million per property records; about $159 million outstanding and a $259.3 million increase per mortgage documents; $100 million added in 2024 bringing financing to $219 million; 2014 site assemblage. - The Real Deal · December 2, 2025St. Regis Sunny Isles construction loan boosted to $418M
Supports: $119 million Bank OZK loan in 2020; $100 million added in 2024; 90 percent presold as of December 2025; end-of-2028 completion; North Tower sales launched in 2024; estimated sellout above $3 billion. - Fortune International Group and Château Group · July 31, 2026Developer announcement: South Tower foundation pour complete, tower set to go vertical (EIN Presswire)
Supports: pour dates of July 24–26; vertical construction “this year”; North Tower “scheduled to break ground in early Q4”; 170 and 150 residences; amenity program; Coastal Construction as general contractor; remaining residences from approximately $5 million. - Fortune International Group and Château Group · April 23, 2026Developer announcement: $113.75 million land loan with City National Bank of Florida (EIN Presswire / National Law Review)
Supports: amount, lender and “pre-development financing” characterization; Berkadia team; North Tower “slated to break ground this summer”; South Tower “nearly sold-out” with 2028 completion. - Project press archive · consulted October 28, 2026srresidencessunnyislesbeach.com/press
Supports chronology: groundbreaking coverage dated August 29 to September 4, 2023; January 2024 deep-foundation coverage; February 2024 North Tower sales launch; January 2025 site-plan revision coverage. - Commercial Observer and The Real Deal · November 2025Madison Realty Capital’s $630 million construction loan for Bentley Residences
Supports: lender context only. - Multi-Housing News · October 28, 2026Fortune, Château Secure $463M for Miami Luxury Condo Development
Cited in our research brief for a 90 percent sold figure. The article could not be retrieved from our environment; its figure is reported here only as a discrepancy and was not relied upon. - Bisnow · October 26, 2026Developers Up Sunny Isles Beach St. Regis Debt Again With $463M Loan
Listed in our research brief; not retrievable from our environment; not relied upon. - Florida Legislature · 2026 Florida StatutesSection 718.202, Sales or reservation deposits prior to closing
Primary legal source for the deposit section, including the alternative-assurance language, the special escrow account, the construction-use exception and its required legend, release rules, escrow-agent requirements, the voidability remedy and the felony provision. Read the statute (Florida Legislature, Online Sunshine). - TheBuyerRebate.com · August 1, 2026Foundation Complete at St. Regis Residences, Sunny Isles Beach
Our prior coverage of the project; chronology and milestone framing carried forward.
Independence and status. TheBuyerRebate.com / Jordan Group is not affiliated with Fortune International Group, Château Group, Madison Realty Capital, Bank OZK, City National Bank of Florida, Berkadia, Coastal Construction, Marriott International or the St. Regis brand. The St. Regis Residences, Sunny Isles Beach are not owned, developed or sold by Marriott International, Inc. or its affiliates; the developer entity uses the St. Regis marks under license. This page is independent buyer-advisory editorial content. Status is described as of October 28, 2026. Loan amounts, presale figures, construction milestones and completion timing originate with the developers, the lender or the publications cited and have not been independently verified by TheBuyerRebate.com; completion dates are developer projections, not commitments. The renderings are developer renderings of the planned towers, not photographs of the construction site. Nothing here is an offer to sell or a solicitation to buy real estate, and nothing here is legal, tax or financial advice; the explanation of Florida Statutes §718.202 is general and is not a review of any purchase agreement. TheBuyerRebate.com and Jordan Real Estate are not a law firm. Rebate amounts depend on the compensation actually received on each transaction and, where financing is involved, lender approval of credits. Information is deemed reliable but is not guaranteed and is subject to change without notice.