Home/News & Intelligence/Faena Residences Miami $817 Million Construction Loan
Faena Residences Miami Secures a Reported Record $817 Million Construction Loan: What It Means for Buyers
Fortune International Group and KAR Properties announced on October 28 that they have closed an $817 million construction loan from Tyko Capital for the two-tower Faena Residences on the Miami River. The sponsors call it the largest construction loan in Florida history, and the public benchmarks support them. For a buyer, the loan answers one question and opens several others: about the schedule, about what the money does and does not protect, and about the deposits that Florida law lets a developer put to work once construction begins.
Loan closed · Groundbreaking reported for November 2026 · Delivery target early 2030
Independent buyer research · Not affiliated with Fortune International Group, KAR Properties, Faena, Tyko Capital or Walker & Dunlop
Five answers, as of October 29, 2026
Each answer is expanded, with sources, further down the page.
- What happened?
- On October 28, 2026, Fortune International Group and KAR Properties announced an $817 million construction loan from Tyko Capital, the private-credit lender led by Adi Chugh and backed by Elliott Investment Management, for Faena Residences Miami at 24 SW 4th Street. Walker & Dunlop arranged the financing. The loan’s rate, term and conditions were not disclosed.
- Is it really a record?
- As far as the public record shows, it is the largest construction loan ever announced in Florida. It exceeds the $772 million Ares-led loan Related Ross announced in December 2025 for two West Palm Beach office towers, which Related itself called the largest ever recorded in the state. Both “record” labels originate with the borrowers; neither has been checked against county mortgage records.
- What is being built?
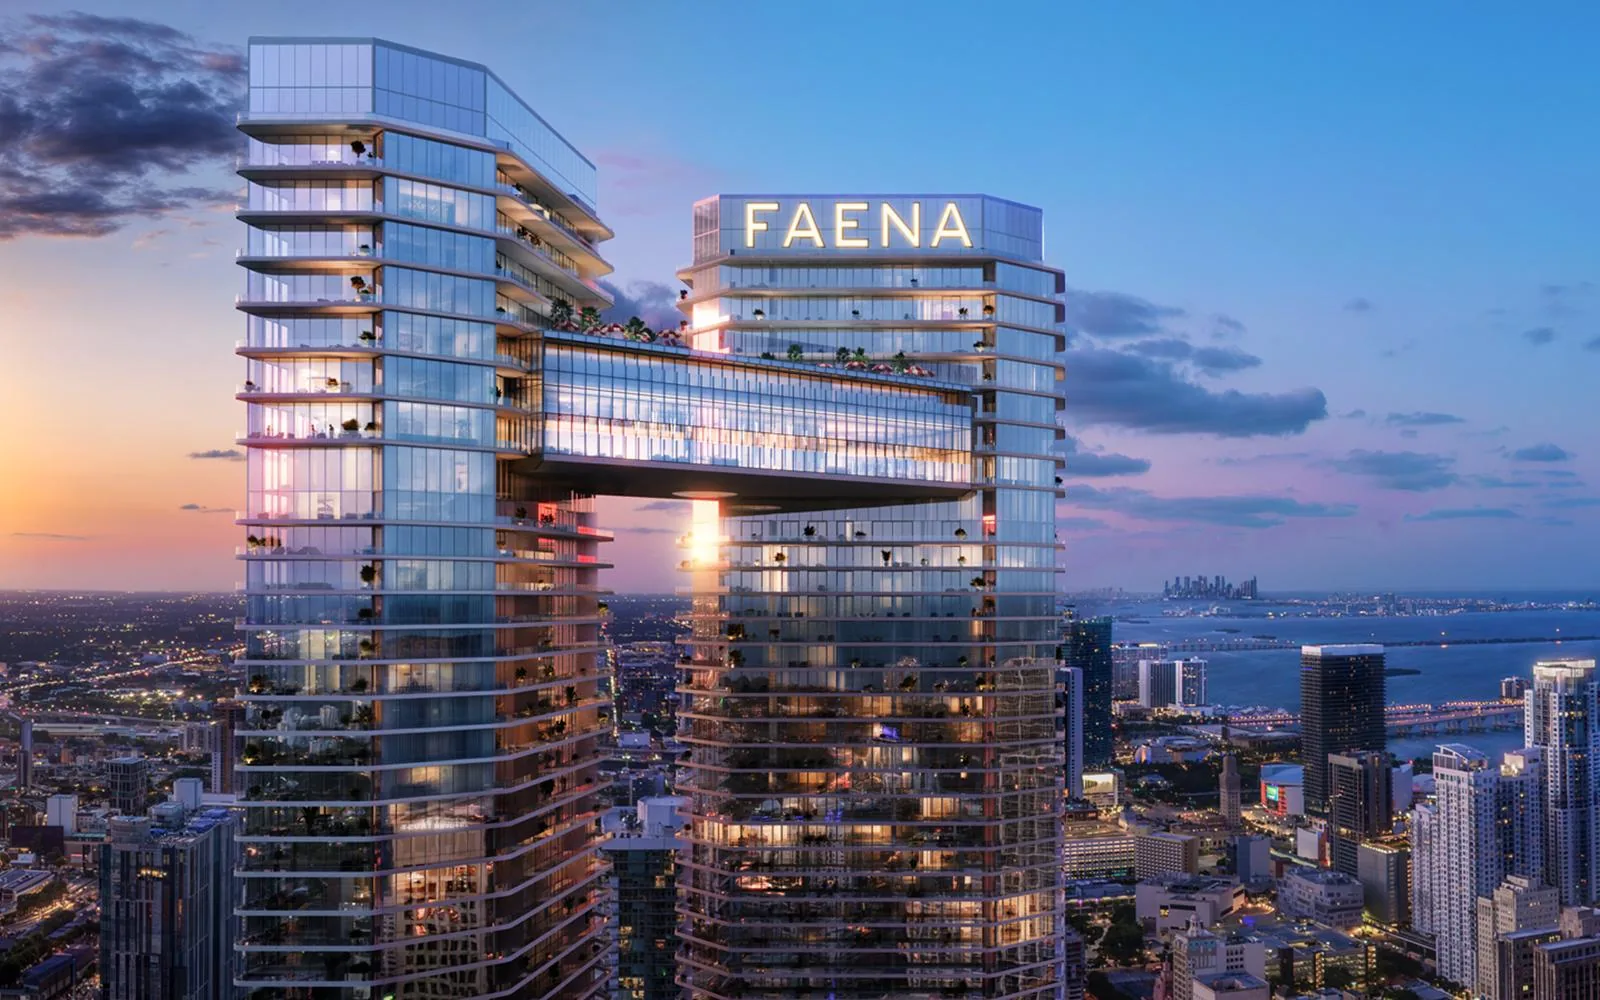
- Two 68-story towers with 217 residences each, 434 in all, on 1.8 riverfront acres across from Brickell City Centre, joined by a sky bridge of roughly 45,000 square feet, according to Commercial Observer and the developers. The Real Deal reports 440 residences, a figure that matches the project’s earlier announcements; earlier materials described 60-story towers.
- What have the developers reported on sales and timing?
- More than $500 million in presales, including a $30 million penthouse that is under contract, not closed. Groundbreaking has been reported for November 2026 and completion for early 2030. All of these are developer statements; the delivery date is a target, not a commitment, and some broker sites still show 2028 or 2029.
- What does it mean for my deposit?
- A construction loan lowers the risk that the project never starts. It does not guarantee completion, and it does not protect deposits above 10% of the price: under Florida Statute §718.202, once construction begins, a developer may spend those funds on construction if the contract says so. The deposit section explains what to read before you sign.
Why this matters to a buyer. Until this week, the only debt reported on the project was a Bank OZK facility for marketing and site work; no senior construction loan had been reported. That gap has closed. What remains is execution risk, timing and the structure of your own contract, and those are the things a buyer can actually investigate. The buyer section sets out how.
$817 million from a private-credit lender, arranged by Walker & Dunlop
The announcement came by news release on Wednesday, October 28, and was carried the same day by The Real Deal, Commercial Observer, CRE-sources, the South Florida Business Journal and the Financial Times. Across the reports we were able to read, the amount, the lender, the borrowers and the arranger are consistent. Edgardo Defortuna, Fortune’s president and chief executive, said the financing “demonstrates the depth of confidence in the project,” as quoted by Commercial Observer.
What no outlet reported, because the sponsors did not disclose it, is the shape of the loan: the interest rate, the term and maturity, the loan-to-cost ratio, whether it is recourse to the sponsors, how much equity sits beneath it, and which presale or construction conditions govern each draw. Those terms decide how much schedule pressure the developer is under, and buyers should assume they exist even though they cannot read them. The $817 million is the construction financing, not the total cost of the project; the balance of the budget typically comes from sponsor equity and from the portion of buyer deposits the law permits a developer to use (see deposits).
Tyko Capital is a private lender rather than a bank, and has become one of the most active sources of very large condominium construction loans in South Florida this year. The Real Deal notes a $507 million Tyko loan closed earlier in October for Terra’s tower at 1250 West Avenue in Miami Beach and a $360 million loan in April for Icon Beach Waterfront Residences in Hollywood. Private credit is typically more expensive than bank debt. That matters to a buyer in one specific way: if the schedule slips, the carrying cost of every month of delay is higher, and a developer under that pressure has less room to absorb problems quietly.
| Date | Capital event at the site | Basis |
|---|---|---|
| 2013 | KAR Properties acquires the riverfront site. | Reported |
| 2015 | KAR launches sales for One River Point, a Rafael Viñoly-designed condominium. Construction never starts; the land stays vacant. | Reported |
| 2022 | Fortune International Group joins KAR as a venture partner; Commercial Observer cites property records showing a $58.8 million purchase of the site. | Property records, per CO |
| 2023 | Bank OZK provides a $38 million loan for marketing costs and site work (Commercial Observer). Bisnow, citing Florida YIMBY, reported $34 million; the recorded amount has not been checked for this page. | Reported; figure disputed |
| October 2024 | Faena brand announced for the project, then described as two 60-story towers. | Reported |
| November 2025 | Public sales-launch event. Defortuna tells the Miami Herald that more than 90 residences, above $300 million, are already under contract; The Real Deal dates the start of sales to 2024. | Developer-reported |
| July 2026 | A $30 million penthouse in the east tower goes under contract, a reported record for the area on price and price per square foot. Not closed. | Developer-reported |
| October 28, 2026 | $817 million construction loan from Tyko Capital, arranged by Walker & Dunlop. Presales reported above $500 million. | Announced; terms undisclosed |
Larger than the $772 million Related Ross loan, and why the label needs a footnote
The comparison every outlet reached for is the $772 million construction loan that Related Ross, Stephen Ross’s West Palm Beach company, announced on December 19, 2025 for 10 CityPlace and 15 CityPlace, two Class A office towers in downtown West Palm Beach. Ares Real Estate led that financing with Monarch Alternative Capital and HPS Investment Partners; Eastdil Secured advised the borrower. Related Ross described it as “the largest construction loan ever recorded in Florida.” The $817 million Faena loan is $45 million larger.
Two caveats apply. First, both records are self-declared. The Faena figure is “described by the sponsors” as the largest in state history, in the careful wording of one trade outlet, and the Related Ross figure came from Related’s own release. Trade reporting checks these claims against other announced deals, not against a census of recorded mortgages, so “record” here means the largest construction loan anyone has publicly announced. Second, the labels differ. The Real Deal, Commercial Observer and CRE-sources call it the largest construction loan of any kind; the Financial Times and the South Florida Business Journal call it the largest condominium construction loan. Both are consistent, because $817 million also exceeds the previous condominium benchmark, PMG’s $668 million loan from Bank OZK and Related Fund Management for the Waldorf Astoria Hotel & Residences Miami in 2024.
| Loan | Amount | Lender(s) | Asset | Record claim |
|---|---|---|---|---|
| Faena Residences Miami October 28, 2026 | $817M | Tyko Capital (private credit, Elliott-backed); arranged by Walker & Dunlop | 434-residence, two-tower condominium, Miami River | Largest construction loan in Florida history — attributed to the sponsors’ release by The Real Deal and WRE News |
| 10 & 15 CityPlace December 19, 2025 | $772M | Ares Real Estate (lead), Monarch Alternative Capital, HPS Investment Partners; Eastdil Secured advised | Two office towers, about 960,000 sq ft combined, West Palm Beach | “Largest construction loan ever recorded in Florida” — Related Ross |
| Waldorf Astoria Hotel & Residences Miami 2024 | $668M | Bank OZK, Related Fund Management | Hotel and condominium supertall, downtown Miami | Largest Florida condominium construction loan at the time — trade reporting |
How to read a “record” as a buyer. The size of a loan is evidence that an institutional lender underwrote the budget, the sponsors and the presales and committed capital: a useful signal, and a better one than a rendering. It is not evidence about your price, your contract or your delivery date, and the carrying cost of debt this size pushes a developer in one direction, toward speed and toward holding buyers to their contracts.
Two 68-story towers, 434 residences and a sky bridge over the Miami River
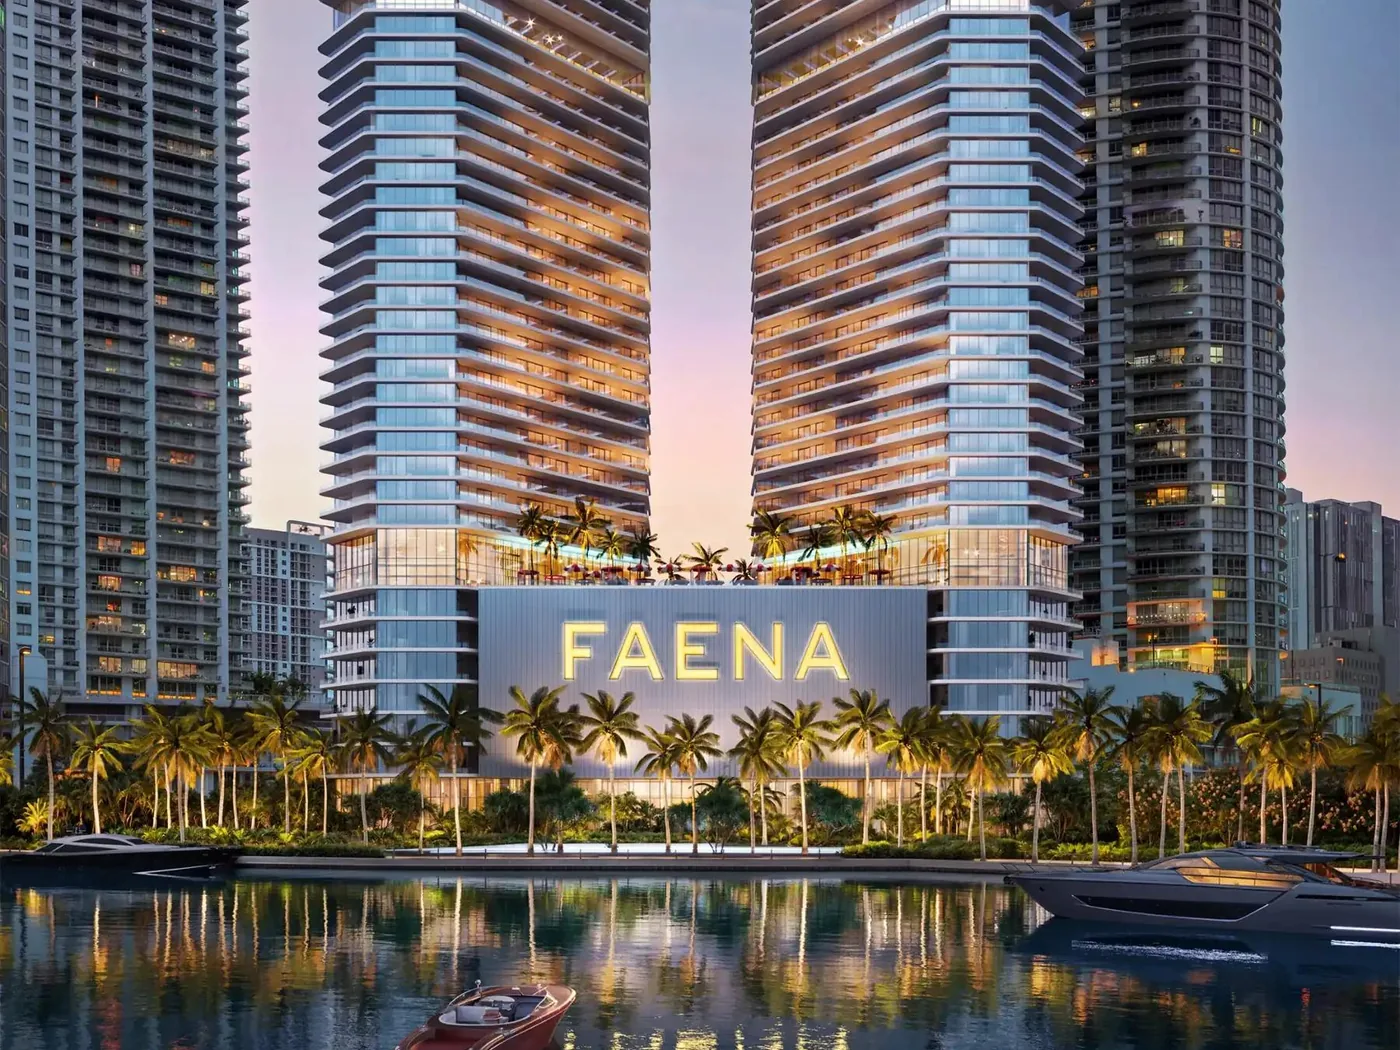
Faena Residences Miami is described by its developers as the Faena brand’s first stand-alone residential project, and it anchors the Faena District Miami River, the riverfront enclave the project’s own materials place near 90 SW 3rd Street; the financing coverage gives the parcel address as 24 SW 4th Street, on about 1.8 acres facing the river across from Brickell City Centre. The towers are the work of Rafael Viñoly Architects, whose One River Point design for the same site was never built; the firm continued the project after Viñoly’s death in 2023.
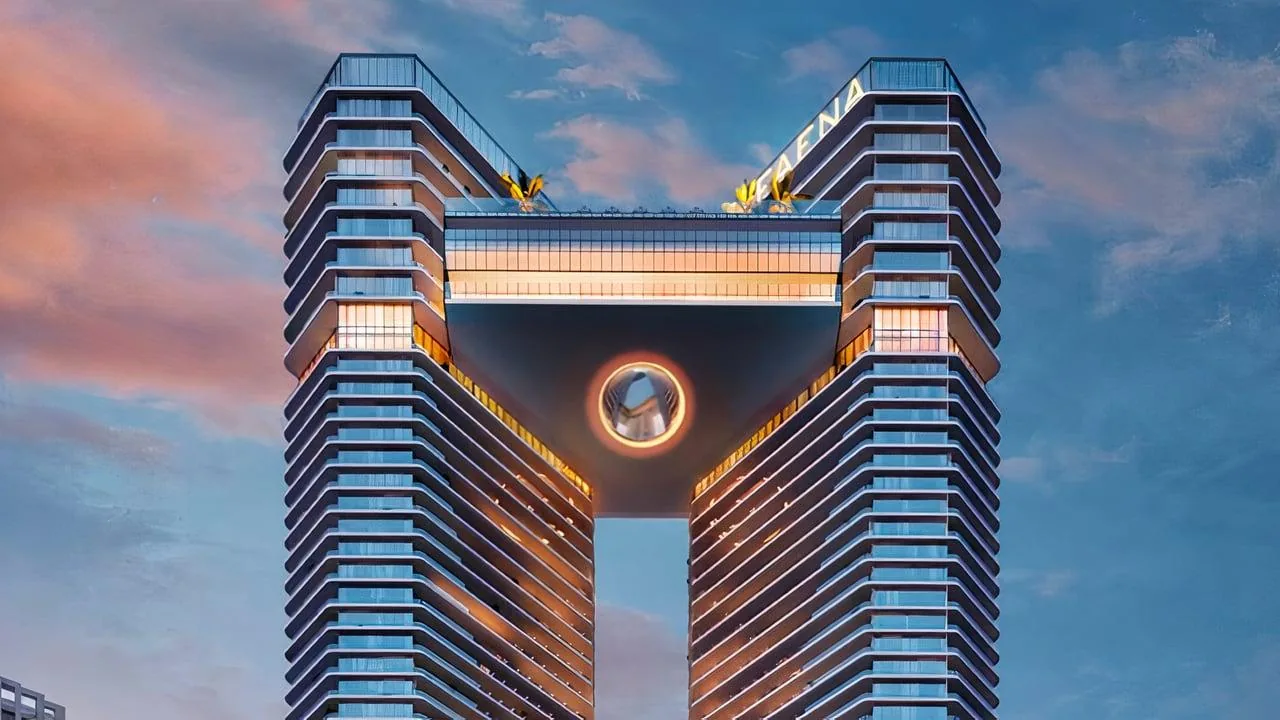
The current specification, as reported by Commercial Observer on October 28 and consistent with what Defortuna described to the Miami Herald at the November 2025 sales launch, is two 68-story towers with 217 residences each, 434 in total. The Real Deal’s October 28 report says 440 residences, which matches the project’s earlier announcements, and the South Florida Business Journal gives 67 stories; the 2024 materials described 60-story towers. Specifications change as a project moves from concept to permit set, and the lesson for a buyer is procedural: the residence count, the floor count and the floor plans that bind the developer are the ones in the purchase contract and the condominium documents, not the ones in a press release.
The towers are joined high above the river by a sky bridge of roughly 45,000 square feet, which the developers describe as a cultural and wellness space for residents, with programming tied to Alan Faena’s cultural model. How the cost of that shared structure is allocated across the two towers, and whether amenities are included in assessments or billed for use, are budget questions to put to the developer before signing. Pricing has been reported from about $1.5 million for the smallest remaining residences to $35 million, in Defortuna’s November 2025 interview; current pricing should be requested directly. For the project itself, see our Faena Residences Miami buyer-rebate guide and the companion what-to-know-before-reserving guide.
$500 million reported under contract, a 2030 target, and dates that do not match
What the developers reported
Commercial Observer and The Real Deal both attribute the presale figure to the sponsors: more than $500 million in sales to date, including the $30 million penthouse that went under contract in July. That penthouse, about 8,200 interior square feet plus some 7,000 square feet outdoors in the east tower, was reported at nearly $3,700 per square foot; The Real Deal noted in October that it would set a record for the area once it closes. It has not closed, and a presale is a contract with deposits, not a sale.
The sales trajectory matters more than any single number. At the November 2025 launch event, Defortuna told the Miami Herald that more than 90 residences, above $300 million, were under contract, more than 20% of the 434. Eleven months later the sponsors report $500 million. What has not been disclosed: the number of contracts, how many are past the statutory rescission period, the deposits actually collected, and the share of buyers who are investors or foreign nationals.
The delivery date
The Real Deal reports completion in early 2030, “according to the release”; Commercial Observer and CRE-sources say 2030; the South Florida Business Journal and CRE-sources report a groundbreaking scheduled for November 2026. That fits the 38-to-40-month construction period Defortuna described a year ago. It does not fit the materials still circulating on broker and marketing sites, several of which show 2028 or 2029 delivery and a “Q4 2029” closing. Those dates predate the financing announcement and should not be relied on. Plan around the contract’s outside completion date and the lender-backed schedule, and remember that delivery dates on Miami supertalls commonly move: the Waldorf Astoria Miami, whose $668 million construction loan closed in 2024, is now reported to anticipate completion in the second quarter of 2028, as we noted in our Waldorf Astoria construction update.
October 2024 · Reported
Faena brand announced
Two towers, then described as 60 stories, on the former One River Point site.
November 2025 · Developer-reported
Sales-launch event
More than 90 residences and $300 million already under contract, per Defortuna; remaining pricing from about $1.5 million. The Real Deal dates the start of sales to 2024.
July 2026 · Developer-reported
$30 million penthouse under contract
East tower duplex; reported area record on price and price per square foot. Not closed.
October 28, 2026 · Announced
$817 million construction loan
Tyko Capital; arranged by Walker & Dunlop; presales reported above $500 million.
November 2026 · Reported target
Groundbreaking
Per the South Florida Business Journal and CRE-sources. Under §718.202, construction starting is the trigger that lets deposits above 10% be used for construction.
Early 2030 · Developer target
Completion
Per the sponsors’ release as reported by The Real Deal. A target, not a contractual date. Confirm the outside date in your contract.
Two loans in 48 hours, and why the headline total overstates the new money
Two days before the Faena announcement, on October 26, Fortune International Group and Château Group closed a $463 million financing from Madison Realty Capital for The St. Regis Residences, Sunny Isles Beach, arranged by Berkadia, which we analyzed in our report on that transaction. Together the two deals total about $1.28 billion, a sum at least one trade outlet had added up by the following morning and the kind of figure that invites a “billion-dollar week” headline. The framing is arithmetically correct and economically misleading.
The St. Regis loan is largely a refinancing. It replaces Bank OZK debt that had grown, through several increases, to a commitment of about $418.3 million by December 2025, and it funds completion of the 170-residence South Tower, which the sponsors report as roughly 80% presold and which poured its foundation in July 2026 (see our analysis of that milestone). The 150-residence North Tower is not covered; it carries a separate $113.75 million pre-development loan and has not started. The amount actually owed to Bank OZK at payoff, and therefore the net new borrowing at St. Regis, has not been published; the simple difference between $463 million and $418.3 million is about $44.7 million, but that is arithmetic on commitments, and no one has confirmed the actual figure. On any reading, the Faena loan is the only one of the two that is new construction money. On that arithmetic, the week brought roughly $860 million of fresh construction capital to Fortune’s projects rather than $1.28 billion; the exact figure depends on the unpublished Bank OZK payoff.
What the two loans have in common
- The same sponsor. Fortune International Group is a co-developer of both projects and, through its sales arm, runs sales at both.
- Private credit, not banks. Tyko Capital and Madison Realty Capital are debt funds. St. Regis refinanced bank debt with private credit; Faena’s construction loan went to private credit from the outset, after a bank pre-development facility.
- Presales first. Both closed after the sponsors reported heavy presales (above $500 million at Faena; about 80% of the South Tower at St. Regis), which is how lenders in this market have been underwriting condominium construction.
Where they differ for a buyer
- Stage. St. Regis South Tower is under construction with its foundation poured; Faena has not broken ground. Faena buyers carry more schedule risk, and for longer.
- Purpose. The Faena loan starts a project; the St. Regis loan refinances and finishes one. A completion loan on a tower that is already rising is a different risk from a ground-up loan on a vacant site.
- Reported delivery. St. Regis South Tower: end of 2028, per a sponsor representative. Faena: early 2030, per the release. Both are targets.
What the loan does for you, what it does not, and what to check before you sign
A construction loan is the single most important piece of third-party validation a pre-construction project can receive before it breaks ground. It is still not a guarantee, and it is not written for your benefit.
What a closed construction loan does
- Funds vertical construction. The project no longer depends on raising senior debt, which until this week had not been reported.
- Reflects a lender’s underwriting. A lender committing $817 million will have underwritten the budget, the sponsors, the presales and the collateral. That is independent scrutiny a buyer cannot replicate.
- Sets a schedule. Loans mature. A maturity date, even an undisclosed one, is a discipline on the developer that marketing dates are not.
- Triggers the next phase for deposits. With financing in place and groundbreaking reported for November, construction starting is also the moment deposits above 10% may be used for construction under Florida law.
What it does not do
- It does not guarantee completion. Loans have conditions and draw schedules; cost overruns, slow sales, litigation or a sponsor default can stop funding. Our Mandarin Oriental Boca Raton analysis shows what a financed project looks like when financing fails.
- It does not protect your deposit. The lender’s mortgage is senior and secured by the land and the building. Your deposit is protected only by the escrow rules in §718.202 and the terms of your contract.
- It does not fix the price or the date. The loan tells you nothing about whether your residence is fairly priced or when it will be delivered. The contract’s outside completion date governs, and Miami pre-construction contracts typically allow extensions well beyond the marketed date.
- It does not make the sales team neutral. The people selling you a residence work for the developer. A record loan gives them a reason to press for a decision; it gives you none to hurry.
Eight things to settle before you sign at Faena Residences, or anywhere comparable
1. Read the deposit schedule against the construction schedule. Unofficial broker sites circulate deposit schedules that differ from one another, all with about half the price paid before closing. None of them is authoritative. The schedule in your contract is, and it tells you how much of your money is in the project at each stage of a build that is targeted for 2030.
2. Find the construction-use legend. If the contract lets the developer use deposits above 10% for construction, Florida law requires a conspicuous, bold-type legend on the first page, above your signature line, saying so. If you see it, understand that money above 10% is going into the building once construction begins and is not sitting in escrow waiting for you. Details are in the deposit section.
3. Identify the escrow agent and get receipts. The statute entitles you to a receipt from the escrow agent on request. Know who holds your first 10%, in which institution, and under what agreement.
4. Pin down the outside completion date and your remedies. Not the marketing date. The contract date, the permitted extensions, and what happens, including to your deposits and interest, if the developer misses it.
5. Confirm the specification you are buying. Unit counts and floor counts have changed since 2024. Your tower (east or west), floor, floor plan, square footage method and view orientation should be fixed in the contract and the condominium documents rather than inferred from a rendering.
6. Ask how the sky bridge and amenities are paid for. Shared structures serving two towers are an assessment question. Ask for the estimated operating budget and which amenities carry use fees.
7. Price the premium. The Real Deal cites a branded-residence markup of 20 to 30 percent over comparable unbranded product. Compare the price per square foot you are quoted with current Brickell and downtown pre-construction and recent resales; our downtown Miami and Brickell guides are a starting point, and for the top of the market, our analysis of Miami’s $30 million-and-up market.
8. Establish independent representation before you register. Who contacts the sales gallery first decides who represents you. Our guide to Miami pre-construction broker registration explains why the order matters; the representation section below explains what it is worth.
What Florida Statute §718.202 protects, and what it lets a developer spend
The statute governs deposits on condominium units sold before construction is substantially complete. It requires the first 10% of the price to be held in escrow, or covered by a state-approved bond or letter of credit, until closing, default or termination; it protects the rest only conditionally. This is an explanation of the law as written in the 2026 Florida Statutes, not legal advice, and we have not reviewed the Faena Residences purchase contract.
The first 10% stays in escrow. Under subsection (1), when a developer sells a unit before construction, furnishing and landscaping are substantially complete, every payment up to 10% of the sale price must be placed in an escrow account (for residential condominiums the state’s Division may accept a surety bond or an irrevocable letter of credit in its place), and the escrow agent must give the buyer a receipt on request. Those funds are released only when the buyer properly terminates and receives them back with interest, when the buyer defaults and the developer receives them, or at closing. A buyer who disputes a disbursement can block it by giving the escrow agent written notice before the funds move.
Everything above 10% goes into a special escrow, with a door in it. Subsection (2) requires payments above 10% to be held in a separate escrow account and bars the developer from using them before closing except as subsection (3) allows. Subsection (3) is the door: if the contract provides for it, and once construction has begun, the developer may withdraw those funds and spend them on actual construction and development costs of the condominium property, including demolition, site clearing, permit and impact fees, utility reservation fees and the architectural, engineering and surveying fees directly tied to construction.
What the money may not buy. The statute prohibits using those funds for salespersons’ salaries, commissions or expenses; for advertising, marketing or promotion; or for loan fees and costs, principal and interest on loans, attorney fees, accounting fees or insurance. In other words, deposits above 10% may build the tower; they may not service the $817 million loan or pay the people who sold you the unit.
The legend. A contract that allows construction use must carry, conspicuously printed in bold type on its first page above the buyer’s signature line, the statement that any payment in excess of 10 percent of the purchase price made to developer prior to closing pursuant to this contract may be used for construction purposes by the developer. If you see that sentence, you have your answer about where deposits above 10% go.
Completion, and the remedy. “Completion of construction” under subsection (4) means a certificate of occupancy for the entire building, or its equivalent, not a topping-out or a marketing milestone. Under subsection (5), a developer who fails to comply with the section gives the buyer the right to void the contract and recover all sums paid, with interest at a statutory rate. The statute was last amended by chapter 2024-244; the current text is at the Florida Legislature’s statutes site.
Why this matters now: with circulating schedules showing about half the price due before closing and groundbreaking reported for November, Faena buyers are approaching the point at which most of their deposits can lawfully leave escrow and become part of a building that will take more than three years to finish. That is normal in Florida pre-construction. It is also the reason to read the contract before the next deposit is due. For the mechanics of deposits, escrow and completion terms generally, see our South Florida pre-construction buyer guide.
Attorney review checklist
- Deposit schedule by amount, date and milestone, and the total due before closing.
- The §718.202(3) legend on page one, above the signature line, and the contract clause that implements it.
- Escrow agent identity, escrow agreement, and the receipt for each payment.
- Outside completion date, permitted extensions and the remedies and interest if it is missed.
- Rescission period (the statutory 15-day cancellation window, which runs from signing or from receipt of the condominium documents, whichever is later) and whether any later amendment reopens it.
- Material-change rights if the developer alters the unit, the building or the budget.
- Assignment and resale restrictions before closing, and any developer fee for assignment.
- Financing contingency: most pre-construction contracts have none. Know how you will close in 2030.
This is a reading list for your attorney, not legal advice. Contract terms vary by project and by residence.
Why independent representation matters when the developer also runs the sales floor
At Faena Residences, as at St. Regis Sunny Isles, the sales team works for the seller: Fortune International Group is a co-developer and, through its sales and brokerage arm, the company presenting the price list. That is simply how the business is structured. It does mean that nobody in the sales gallery is paid to tell you what the delivery date means, which deposit leaves escrow when, or how the price per square foot you are quoted compares with the tower across the river. Someone should, and that person should work for you.
TheBuyerRebate.com and Jordan Real Estate represent buyers independently, with attorney-reviewed transaction support. Eligible buyers receive up to 50% of our buyer-agent commission back at closing. Whether a rebate applies, and how much, depends on the compensation the developer makes available in your transaction, your representation agreement and lender and closing requirements; a rebate is never guaranteed, and we confirm the figure in writing before you sign. How the rebate works, step by step, is in our Florida Buyer Rebate Guide; why you must establish representation before your first contact with the sales gallery is in our guide to pre-construction broker registration.
Considering Faena Residences Miami? Talk to us before you register with the sales gallery.
We can walk you through the deposit schedule and the §718.202 legend with your attorney, compare the pricing you are quoted with the market across the river, and estimate the rebate available in your transaction. Eligible buyers receive up to 50% of our buyer-agent commission back at closing. Rebates are never guaranteed and are confirmed in writing before you sign.
(786) 550-6294- Looking at a specific residence? Tell us the tower, floor and line and we will tell you what to ask about the contract before your next deposit.
- Already under contract? We can still help you understand what the financing, the schedule and the deposit rules do and do not change for you.
Check Your Faena Residences Rebate
No obligation. This form does not register you with the developer or any sales gallery.
What this page is based on
Research cutoff: October 29, 2026. Facts stated by the developers or taken from their news release are labeled developer-reported; facts drawn from property or statutory records are labeled as such; everything else is journalism, and we say whose. The sponsors’ release and the recorded mortgage were not obtained for this page, so loan terms are described as undisclosed rather than inferred.
Source Register
- Commercial Observer · October 28, 2026Fortune Lands Record $817M From Tyko Capital to Build Miami Faena Condo Towers
Supports: lender, borrowers, Walker & Dunlop team, “Florida’s largest-ever construction loan,” $772 million benchmark, 68 stories, 217 residences per tower, 1.8 acres, 24 SW 4th Street, $500 million presales and $30 million penthouse attributed to the sponsors, 2030 completion, Defortuna quotation, 2022 site purchase ($58.8 million, property records), 2023 Bank OZK $38 million loan, Tyko’s Elliott backing. - The Real Deal · October 28, 2026Faena Residences on the Miami River scores $817M construction loan
Supports: news-release basis, loan “closed” by Fortune and KAR, Walker & Dunlop as arranger, “largest such loan in Florida history,” 440 residences, early-2030 completion “according to the release,” sales start dated to 2024, penthouse record “once it closes,” other Tyko loans (Terra’s 1250 West Avenue; Related Group and BH Group’s Icon Beach), branded-residence markup of 20 to 30 percent. - CRE-sources · October 28, 2026Faena Residences Secures Record $817M Construction Loan (title as indexed; page not retrieved)
Supports: “largest construction loan reported in Florida history,” $772 million benchmark, 68 stories, 434 residences, 1.8 acres, November 2026 construction start, 2030 completion. Cited from the research file; the page could not be retrieved directly when this article was prepared. - South Florida Business Journal · October 28, 2026Faena Residences Miami secures record $817M loan
Supports: “largest condo construction loan in Florida history,” 67 stories, groundbreaking scheduled for November. Paywalled; cited from the research file. - Financial Times · October 28, 2026“$817mn skyscraper deal” by an “Elliott-backed private lender” (headline and standfirst as indexed; full title not confirmed)
Supports: “Florida’s largest-ever condo construction loan” (headline and standfirst only; body paywalled and not relied on). - WRE News · October 28, 2026Faena Miami Towers Secure $817M Construction Loan
Supports: record “described by the sponsors,” presales as sponsor-reported commitments rather than closings, $817 million as financing amount rather than total cost. - The Real Deal · July 16, 2026Faena Miami River sells $30 million record penthouse
Supports: penthouse under contract, east tower, duplex with private rooftop pool per the developers’ release, about 8,200 interior and 7,000 exterior square feet, nearly $3,700 per square foot, 2025 public sales launch. - Miami Herald · November 2025 (interview of November 15, 2025)Faena is building condos along the Miami River, and they’re selling for millions
Supports: 434 residences, 68 stories, 45,000-square-foot bridge, more than 90 residences and $300 million under contract at launch, pricing from $1.5 million to $35 million, 38-to-40-month construction period, project history (One River Point, 2022 partnership). Interview with Edgardo Defortuna; all sales figures developer-reported. - Bisnow · December 19, 2025Stephen Ross Gets Largest Construction Loan In Florida History From Ares-Led Group
Supports: $772 million, Ares with Monarch and HPS, 10 and 15 CityPlace, Eastdil Secured, Related Ross’s “largest construction loan ever recorded in Florida” characterization, $668 million PMG Waldorf Astoria predecessor (Bank OZK and Related Fund Management). Corroborated by GlobeSt, December 19, 2025. - Bisnow · October 2024Developers tap Faena to brand 60-story, two-tower project on Miami River
Supports: 2024 brand announcement and the 60-story description then in use; $34 million Bank OZK figure attributed to Florida YIMBY. - Commercial Observer, CRE-sources and The Real Deal · October 26–27, 2026St. Regis Residences Sunny Isles Beach $463 million financing
Supports: Madison Realty Capital, Berkadia, refinancing of Bank OZK debt, 170-residence South Tower, about 80% presold, end-of-2028 South Tower target, $113.75 million North Tower pre-development loan. Bank OZK commitment history ($418.3 million by December 2025) from Bisnow and Commercial Observer, December 2025. - Florida Legislature · 2026 Florida StatutesSection 718.202, Sales or reservation deposits prior to closing
Primary legal source for the deposit, escrow, construction-use, legend, completion and remedy provisions described above; last amended by chapter 2024-244. Linked above as a primary document. - TheBuyerRebate.com · 2026Faena Residences Miami buyer-rebate guide and buyer guide; St. Regis Sunny Isles foundation analysis; Waldorf Astoria Miami construction update
Our own prior reporting, cited for project background, the July 2026 penthouse coverage and the delivery-slippage comparison.
Independence and status. TheBuyerRebate.com / Jordan Group is not affiliated with Fortune International Group, KAR Properties, Faena, Tyko Capital, Elliott Investment Management, Walker & Dunlop, Madison Realty Capital, Related Ross or any lender or developer named here. This page is independent buyer-advisory editorial content. Status is described as of October 29, 2026 and will change as construction proceeds. Presale figures, the record characterization, the groundbreaking and completion dates are developer statements that have not been independently verified; loan terms were not disclosed; no recorded mortgage was reviewed. The renderings are the developers’ conceptual images, reproduced for editorial context, and the completed buildings may differ. Nothing here is an offer to sell or a solicitation to buy real estate, and nothing here is legal, tax or financial advice; the discussion of Florida Statute §718.202 is a general explanation and your purchase contract should be reviewed by a Florida attorney. Rebate amounts depend on the compensation actually received on each transaction and, where financing is involved, lender approval of credits; a rebate is never guaranteed. Information is deemed reliable but is not guaranteed and is subject to change without notice.